Bank capital and the minimum corporate tax
International Tax and Public Finance, 2026.
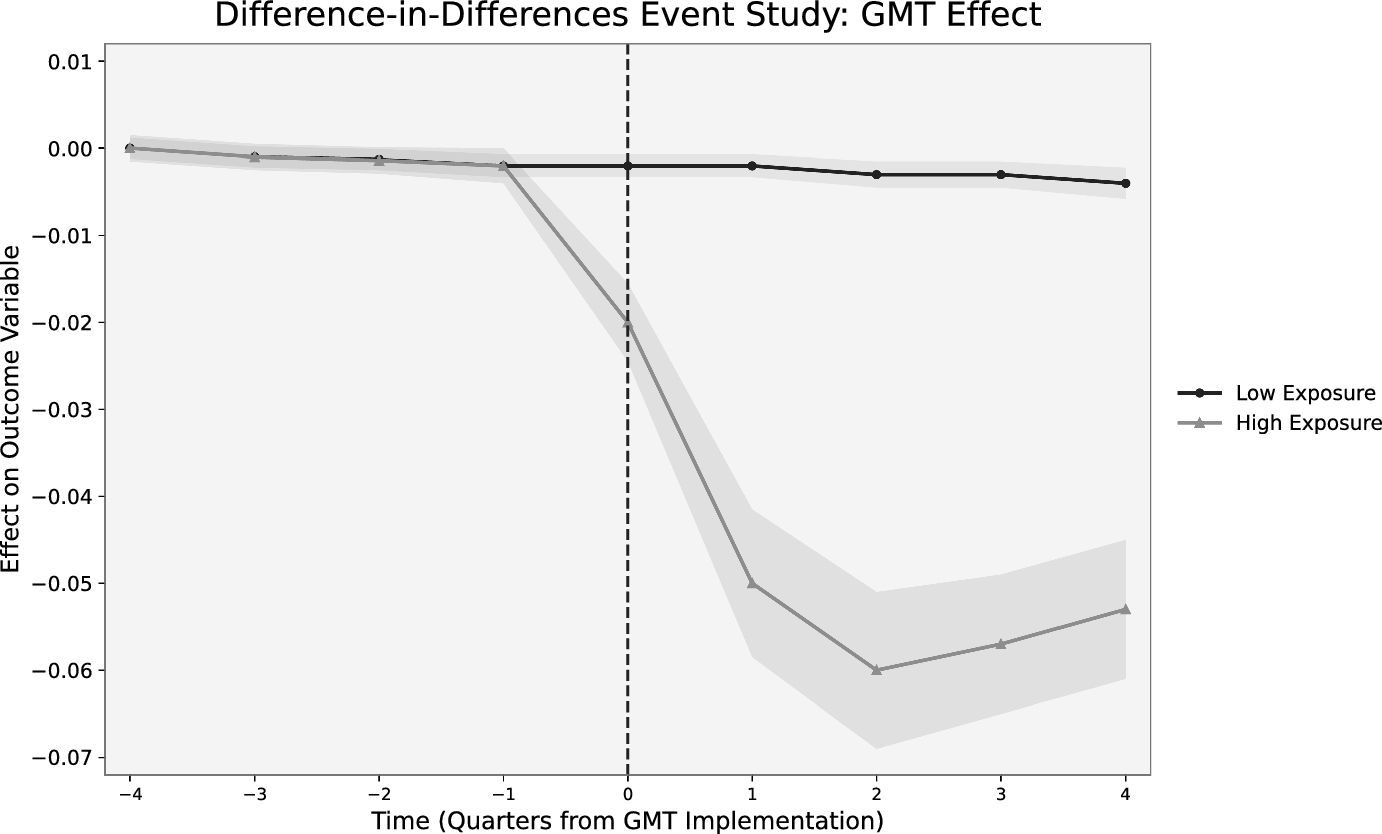
Abstract. This paper examines how the Pillar Two global minimum tax affects banks' profits and regulatory capital. Using quarterly bank data from 2014 to 2024, it compares banks with different levels of exposure to low-tax jurisdictions before the reform. More exposed banks experience modest declines in profitability and Tier 1 capital buffers after 2024. The reduction in capital buffers is most pronounced among banks that entered the reform with limited capital headroom.